Collision
Repairs after a wreck
Two quotes can look the same on paper and behave nothing alike the day something goes wrong. I lay the differences out early, so the policy you sign still makes sense months later.
Compare Your OptionsRepairs after a wreck
Tows, jumps, flat tires
Damage you cause others
Stolen cars, hail, storms
Most people buy car insurance while their mind is already on something else. Sit with me for ten quiet minutes and the better option usually walks out on its own.
Mileage, where the car sleeps, safety gear and how you pay all move the number. I shift two or three of those and the yearly cost often drops further than changing carriers would.
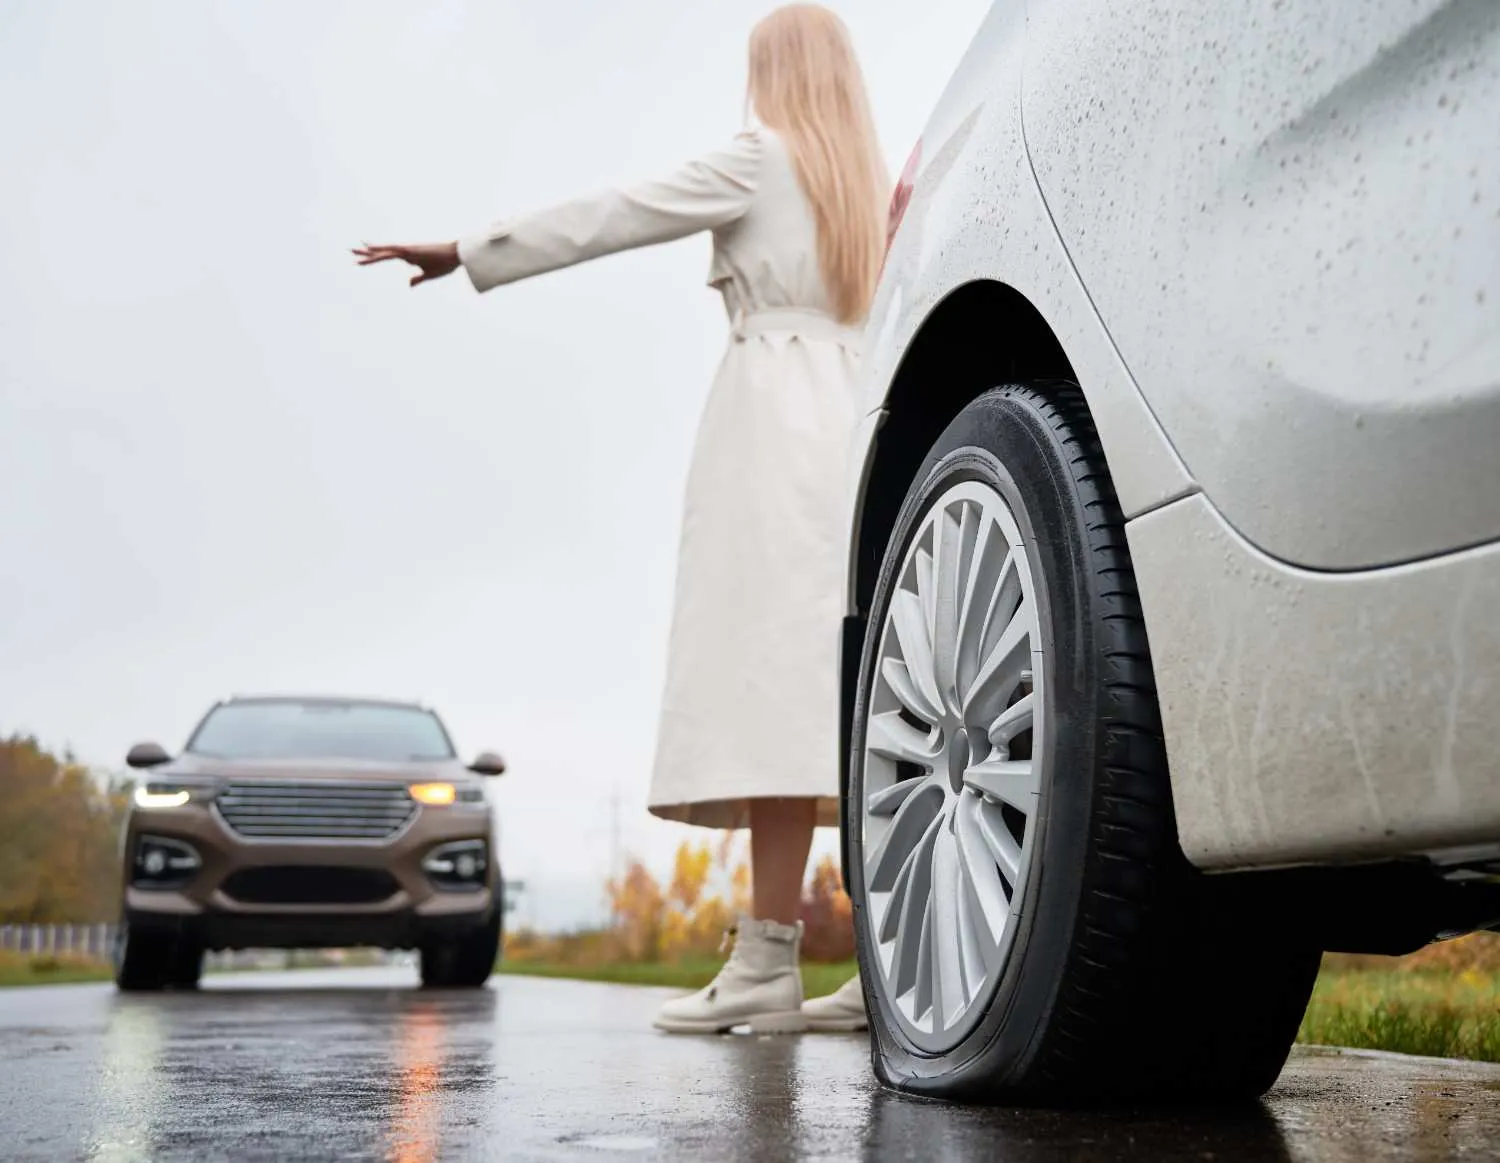
A claim comes down to photos, calls and timing. I tell you what to shoot at the roadside and how many rental days you hold, so one rough afternoon stays exactly that.
State minimums are a floor, never a target. When the car you hit is newer than yours, thin limits empty out and I would rather you never learn that the hard way.
A long commute, a car that mostly sits, a teen driver added to the policy. Each one changes what good coverage looks like. Tell me how the car gets used and I can narrow the search fast.
A few notes from drivers I helped sort out their car insurance.
The five I hear most often before someone changes their car cover, answered without a pitch attached.
Only if rental reimbursement sits on the policy. It pays a daily rate for a fixed number of days, so that cap is the first thing I read. A thin daily limit runs out well before most body shops finish.
Usually not on its own. I have seen a single minor ticket cost less than losing a safe driver discount would. The second one inside three years is the one that stings.
It works if you could hand over the higher amount tomorrow without flinching. Moving from 500 to 1000 trims most premiums, and I only suggest that trade when the money is genuinely sitting spare.
That is precisely what uninsured motorist coverage is for. Leave it off and your repairs and medical bills come back to you for a crash you never caused.
Once a year, plus any time something changes: a move, a different car, a driver added or dropped. Rates drift upward quietly between renewals, and I have never seen loyalty alone hand anybody a discount.